How to Buy Real Estate with a Self-Directed IRA
Buying property with retirement money does not necessarily mean withdrawing it from your IRA and paying taxes first. David Moore, CEO of IRA Advantage, and Tom Moore, President of IRA Advantage, discuss how to buy real estate with a Self-Directed IRA while keeping the money inside the retirement account. They cover two ways to purchase property, how custodian fees differ, and why personal money and activities must stay separate from the IRA’s investment.
Two Approaches for Buying Real Estate with a Self-Directed IRA Account
There are two main approaches to buying real estate with a Self-Directed IRA: have the custodian purchase the property directly for your account or use an IRA-owned LLC that you manage. Both start with choosing a custodian (a company that holds and administers retirement accounts) that allows real estate investments.
With the first approach, you instruct the custodian to buy the property for your IRA. The custodian reviews the purchase, signs transaction documents, and sends the money. You do not need a limited liability company, or LLC, to buy property this way.
The second approach is a checkbook IRA, also called an IRA LLC. Your IRA invests in an LLC, which then buys the property. In this arrangement, your IRA generally owns the entire company through its custodial account, and you serve as the manager.
To fund the LLC, money moves from your existing retirement account to the self-directed custodial account. The custodian then invests that money in the LLC, depositing it into the company’s bank account. You make offers in the LLC’s name and pay from that account.
This lets you negotiate purchases and arrange payments without having the custodian process each property transaction. At IRA Advantage, this IRA LLC setup process usually takes about a month. Once the company is established and funded, you can make offers and arrange payments on its behalf without having the custodian process each property purchase.
Understanding Custodian Fees and Requirements
When choosing a custodian, there are two important things to consider: how they charge and what they require to establish and manage an IRA LLC. These affect both your ongoing costs and your ability to handle purchases yourself.
The fee structure affects how much you pay each year to hold your investments. Some custodians charge a basic annual fee plus a fee for each investment. Under that structure, three properties owned directly by your IRA may mean three separate fees. If your IRA instead owns one LLC that holds those same properties, the custodian counts only the LLC as one investment. Other custodians base their fees on the value of the investments in your account. Under that structure, the amount you pay depends on the values the custodian has on record. However, if an investment loses value, the custodian may continue charging based on its previous value until the change is established. David recalls a client whose million-dollar loan investment became worthless, but the custodian continued charging based on the full $1 million until the loss was established.
The custodian’s requirements determine how you set up the LLC and whether you can manage its purchases and payments yourself. Some custodians allow the IRA owner to serve as manager, while others do not. They may also require annual reviews or written statements from your tax or legal advisers. Before funding the LLC, the custodian must accept its operating agreement (the document describing the company’s ownership and management). Tom cautions that a standard LLC agreement may not address the rules that apply when an IRA owns the company. Simply registering an LLC is therefore not enough: its agreement needs to be written for IRA ownership and accepted by the custodian before retirement funds can be invested in it.
Avoiding Prohibited Transactions and Understanding Potential Taxes
Buying property through your IRA involves two main considerations: avoiding prohibited transactions and understanding potential taxes from borrowing or running a business.
You cannot treat your IRA’s property or money as your own, and certain personal payments or activities can create prohibited transactions. David and Tom give several examples: signing a purchase agreement in your own name and transferring it to your IRA, paying the IRA’s deposit with personal money, doing renovation work yourself (even without pay) or staying at the property while your IRA owns a share. Setting up and funding the IRA LLC before making an offer lets you sign the agreement in the company’s name and pay from its account. You can manage the company’s purchases and payments, but you cannot personally use or renovate its property.
Keeping a property inside your IRA does not always mean the income is free from taxes. For example, if your IRA pays for half the purchase and borrows the other half, Tom explains that roughly half the property’s net income could be taxable within the IRA. This can happen even with a Roth IRA. The loan must also qualify based on the property, without relying on your personal income or credit. Flipping houses raises a separate tax issue: if your IRA buys properties to fix and resell, that activity may be treated as a business, and the profits can be taxable.
Plan for How You Will Use the Property
Your intended use should guide the purchase. A property you plan to rent out may require a different approach from one you hope to make your retirement home. If you eventually want to live in the property, discuss that goal before buying it through your IRA. As David puts it, “It’s not the deal, it’s the destination.” Discussing those goals before purchasing can help you choose an account and ownership arrangement that fit how you plan to use the property.
If you are considering buying real estate with retirement funds, contact IRA Advantage to compare account options and understand the purchase requirements before making an offer.
The Guys With All The Answers…
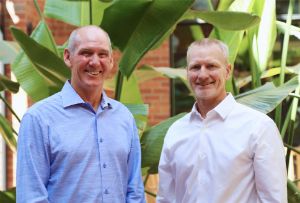 David and Thomas Moore, the co-founders of Equity Advantage & IRA Advantage
Whether working through a 1031 Exchange with Equity Advantage, acquiring real estate with an IRA through IRA Advantage or listing investment property through our Post 1031 property listing site, we are here to help Investors get where they want to be. Call them today! 503-635-1031.
FAQs About Buying Property with a Self-Directed IRA
Do I need a checkbook IRA to buy real estate with IRA funds?
No. Your IRA can purchase property directly or through an IRA LLC without first paying the money to you.
Do I need a checkbook IRA to buy property?
No. You can use a Self-Directed IRA whose custodian handles the property purchase for your account. A checkbook IRA is another option: your IRA owns an LLC, and you manage the purchase and payments through that company.
Can I renovate my IRA’s property myself?
No. You cannot personally perform renovation work on property your IRA owns, even if you have construction experience or do the work without pay. Tom explains that providing this labor creates a prohibited transaction. Managing an IRA LLC allows you to handle its purchases and payments, but it does not allow you to do the renovation work yourself.